
Deposit you would need (2.5%)
£7,500
On a £300,000 home. That is £7,500 less upfront than the usual 5% deposit.
- Government equity loan (20%)
- £60,000
- Mortgage you would need (77.5%)
- £232,500
You could buy a £300,000 new build with £7,500 down.
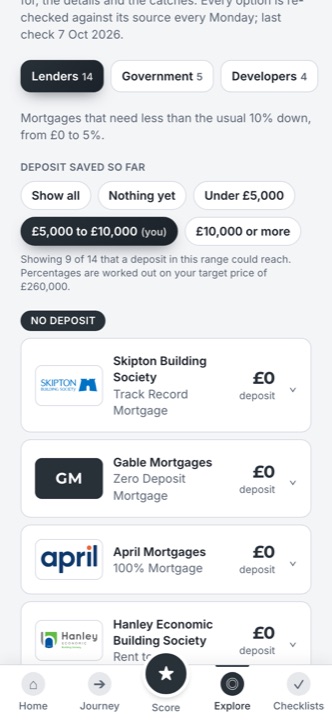
Your monthly payment, whether you could qualify, and the routes that could beat this scheme for you
Free in the app. Your numbers come with you. Thirty seconds, no card.
Unlock my full result, freeHow it works
- 1You put down 2.5%. Half what the old Help to Buy asked for. You can put down up to 15% if you have it.
- 2The government lends 20%. Interest-free for the first five years, then interest rises gradually. You repay its share of what the home is worth when you sell or repay, not a fixed sum.
- 3A mortgage covers the rest, about 77.5%, from a lender in the scheme. New builds in England only, from developers who have signed up. Opens spring 2027.
Things to know before you count on it
- Confirmed at the Budget on 28 October 2026: £4.7bn for around 70,000 households in England, opening spring 2027.
- Price caps: £650,000 in inner London and £500,000 in outer London are confirmed. Elsewhere the cap comes from local median prices and has not been published area by area.
- Income caps are not confirmed. £110,000, and £140,000 in London, were reported before the Budget. Treat the income check as a guide.
- You owe a share, not a sum. If the home rises in value, so does what you repay the government.
- Funding is limited each year, so places can run out. Developers in the scheme contribute to its cost.
- Lifetime ISA news from the same Budget: from 29 October 2026 the charge for using it on a home above £450,000 drops from 25% to 20%, and a new First Time Buyer ISA replaces it for new savers from April 2029.
Illustrative estimates from the Budget announcements on 28 October 2026. Final scheme rules have not been published. This is guidance to help you prepare, not a mortgage decision or financial advice. Your home may be repossessed if you do not keep up repayments on your mortgage. Speak to an FCA-authorised mortgage adviser before you decide.
The Homebuyers Club
The scheme opens in spring. Be ready before it does.
Places are limited and the first in line will be the people with their numbers straight. The Homebuyers Club shows you how mortgage-ready you are, what to fix first and every low-deposit route, so you can move the day it opens.
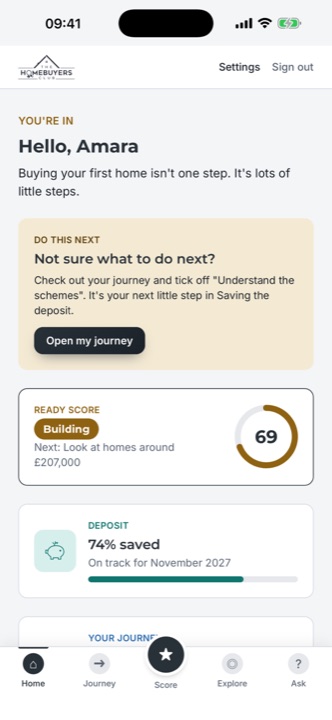
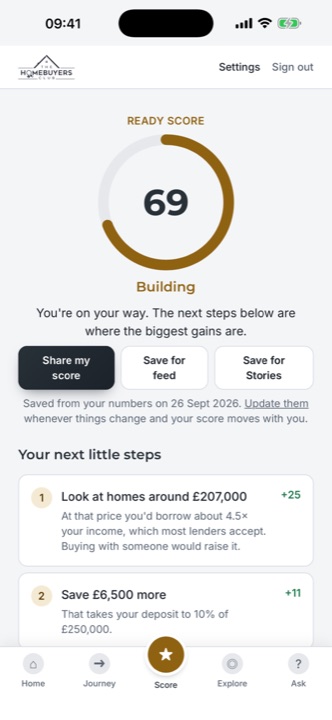
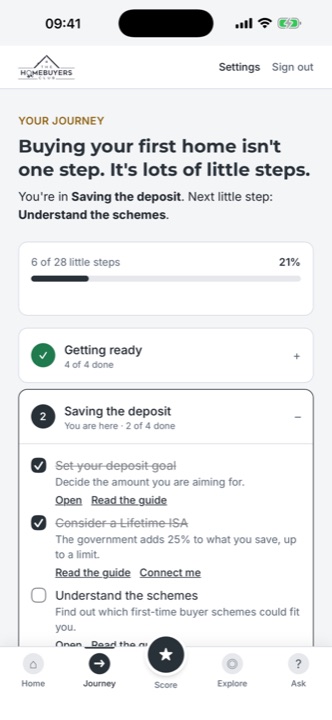
No card, no trial. Sign in with Apple or an email link.